Thrift Savings Plan
FRTIBBusinessVerified
- 1.91K Reviews
- 4.8
- Downloads
- 500,000+
- Price
- Free
Screenshots
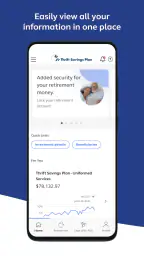
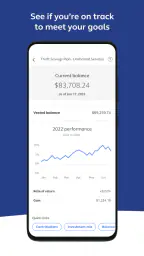
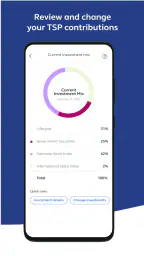
 Analysis by Appwesome
Managing a retirement account is rarely difficult because of one complicated task. The real problem is usually the scattered routine around it: remembering where to sign in, checking whether a contribution changed, reviewing the balance, and making a decision without turning a quick check into an afternoon project. I found Thrift Savings Plan useful because it puts that account-focused work into a dedicated mobile app instead of making me depend on a general browser session every time.
Developed by FRTIB, this free Business app is aimed specifically at people with a Thrift Savings Plan. It is available for Everyone, runs on Android and iOS devices that meet its operating-system requirement, and has built a strong audience with over 500 thousand installs. Its average rating is 4.8 from around 5.5 thousand ratings, which suggests that many users find the focused approach worthwhile. My own view is more practical: it is a good companion for routine account management, but it is not a replacement for learning how retirement contributions and investment choices work.
Turning a scattered money task into a repeatable routine
I find the most useful change here is not that retirement planning becomes simpler, but that checking the account can become a small, repeatable task instead of a browser detour. I would tie that check to an existing cue, such as reviewing a pay statement, so the app supports a routine rather than encouraging aimless balance-watching. That practical habit leads naturally to the question of what to look for once I open it.
What I would do before opening the app
The most useful way to approach this app is not to open it whenever I feel anxious about retirement. That creates a checking habit without necessarily improving my decisions. I get more value by deciding beforehand what I want to accomplish: confirm that a contribution was reflected, review the current account position, check an allocation, or simply make sure nothing needs attention.
That small change matters. A retirement account is a long-term system, while a phone encourages short bursts of attention. If I open the app without a purpose, a balance can become an emotional scorecard. If I open it with a defined question, the same screen becomes a practical checkpoint. I would therefore pair the app with a calendar reminder tied to a sensible review rhythm rather than checking it repeatedly throughout the day.
This is also where the app’s narrow focus helps. I do not have to sort through credit-card offers, banking promotions, or unrelated financial products. The experience is centered on the Thrift Savings Plan, so the workflow begins with the account itself. For someone who already knows why they are signing in, that concentration is more useful than a broad personal-finance dashboard.
Capturing the information I actually need
When I use a financial app responsibly, I try to separate facts from reactions. The facts might include the current balance, recent account activity, contribution information, or the investment allocation I intended to use. The reaction might be excitement after a rise or worry after a decline. Thrift Savings Plan is most helpful for the first group: it gives me a direct place to review account information instead of relying on memory or an old screenshot.
Other Stories to Read



A practical workflow is to open the app, authenticate, confirm the account overview, and then write down only the item that affects my next action. If everything looks as expected, the next action may be none. That is an important outcome. A good retirement routine should not force a change every time I check in.
I also like the idea of using a short note outside the app for decisions that need context. For example, if I change an allocation or adjust a contribution through the appropriate account process, I can record why I did it and when I want to review it again. The app remains the place for current account information, while the note prevents me from making a new decision simply because I forgot the reasoning behind the previous one.
Why the dedicated approach beats my usual browser workaround
Before using a dedicated account app, my alternative would be a mobile browser: find the correct TSP page, navigate through a general website, sign in, and then locate the account area. That approach can work, especially for users who rarely access the account, but it adds friction at exactly the moment when I want a quick, focused check.
A general budgeting app offers a different kind of convenience. It may help me see spending, debts, and multiple accounts in one place, but it is not the right tool for understanding the details of a Thrift Savings Plan. It can also turn a retirement review into one more item in a crowded financial feed. Thrift Savings Plan makes more sense when the goal is direct access to this particular account rather than an all-in-one view of personal finances.
The trade-off is that the app is not a complete money-management system. I would not install it expecting budgeting categories, bill planning, or a broad net-worth dashboard. Its value comes from being specific. If I need a single place for every financial account, a broader service may be more convenient, while this app is the better choice for focused TSP access.
Building a routine that does not depend on motivation
The strongest use case I found is a repeatable routine connected to an existing event. A user might review the app after checking a pay statement, after confirming a payroll change, or during a scheduled monthly financial review. The exact timing is less important than the trigger. When the app is attached to something already happening, I am less likely to forget it and less likely to open it randomly.
My preferred sequence would be simple. First, I sign in and confirm that I am looking at the expected account. Next, I review the information relevant to the reason I opened the app. Then I compare it with my own record, such as a pay statement or a note about a recent change. Finally, I close the app unless there is a clear task to complete.
This approach avoids a common mistake: treating every visible change as a command. Retirement accounts move over time, and a mobile screen can make short-term changes feel more urgent than they are. The app can show me what is happening with my account, but it cannot decide whether a change fits my long-term plan. That judgment still belongs to me, and sometimes to a qualified financial professional.
Another useful habit is separating account monitoring from account education. If I do not understand a fund choice, contribution rule, or transaction, I should not try to solve that uncertainty by repeatedly refreshing the app. I would use the app to identify what I need to understand, then consult the relevant official TSP resources before acting. This distinction makes the app part of a sustainable productivity system rather than a source of financial noise.
Everyday scenario: checking a payroll change
Imagine that I changed my contribution through my employer and want to know whether the account reflects the new arrangement. Instead of opening a browser and searching through several pages, I use the app during my regular payday review. I check the account information, compare it with the pay statement, and record whether the result matches my expectation.
If it does match, I am finished. If it does not, I have a specific issue to investigate rather than a vague feeling that something is wrong. I can check whether the change was expected to appear immediately, review the relevant account information, and contact the appropriate support channel if needed. The app does not eliminate every step, but it gives the process a clear starting point.
This is more valuable than it may sound. Small administrative uncertainties are easy to postpone, especially when retirement accounts feel distant. A focused mobile check reduces the effort needed to notice a discrepancy early. It also gives me a consistent place to begin when I need to verify what is happening.
Where the experience can break down
The first failure point is authentication. A financial app has to protect access to sensitive account information, so signing in may feel less immediate than opening a casual productivity app. If I am in a hurry, a login interruption can tempt me to postpone the check entirely. My practical solution is to keep my account-recovery information organized and avoid waiting until an urgent moment to discover that I cannot sign in.
The second failure point is confusing visibility with control. Seeing account information on a phone does not mean every change can or should be handled from the same screen. Some tasks may still require a separate process, additional verification, or attention to payroll timing. I would use the app as the account-access layer, not assume that a mobile interface replaces every administrative route connected to the TSP.
The third is interpretation. A clean account overview can make financial decisions look simpler than they are. The app is convenient for checking what is in the account, but convenience should not encourage impulsive allocation changes. If I cannot explain why I am making a change, I would pause rather than use the app as a button for reacting to market movement.
There is also the ordinary limitation of a dedicated app: it does not bring together my entire financial life. I still need other tools for household cash flow, emergency savings, taxes, and goals outside the TSP. That is not a defect in its main purpose, but it affects how I would organize my phone. I would place it alongside, not instead of, a broader financial system.
What the current release means for compatibility
The current version is 7.2.0, and the stated minimum operating-system requirement is version 12. That makes checking device compatibility an important step before planning to rely on it daily. Users with older phones may need to update their operating system or use another access method, while users on supported devices should still keep the app and operating system maintained for a smoother account-access routine.
I appreciate that the app is free, because cost is not an extra barrier to accessing a workplace retirement account from a phone. The free price does not make the financial decisions themselves effortless, of course. It simply means the app can serve as a practical account tool without adding a subscription decision to the workflow.
Who should adopt it
I would recommend Thrift Savings Plan to TSP participants who want a direct, mobile way to review their account and who are willing to build a calm routine around that access. It is particularly useful for someone who checks payroll changes, wants a dedicated account view, or finds browser-based access too cumbersome for occasional reviews.
It is also a good fit for users who prefer to keep retirement information separate from everyday banking. Rather than mixing a long-term workplace account into a constantly changing spending dashboard, they can use this focused tool when the purpose is specifically TSP management.
I would be more cautious recommending it to someone who expects a complete financial planner. If your main need is budgeting, tracking several institutions, forecasting household cash flow, or receiving broad investment education, this app will not be enough on its own. A general finance tool or direct web resources may serve those needs better, with this app retained for account-specific checks.
New investors should also avoid treating the app as personal advice. It can make access easier, but it cannot replace learning the basics of contributions, investment choices, risk, and retirement planning. In my experience, the best results come when the app handles the repetitive checking while a separate learning process handles the more complicated decisions.
My final take on its place in a financial system
After using it as a focused account companion, I see Thrift Savings Plan as a practical utility rather than an all-purpose financial application. Its strength is the reduction of friction between wanting to verify something and actually reaching the relevant TSP account. That narrow purpose is exactly why it can fit neatly into a sustainable routine.
The app works best when I decide what I need to check, review the information once, compare it with the record that prompted the visit, and then move on. It is less useful when I expect it to explain every investment question, manage every part of my finances, or tell me how to react to short-term account changes.
With its free access, Everyone age rating, focused Business category, and strong reception from its user base, it is an easy recommendation for eligible TSP participants using a compatible device. The important qualification is that the app improves access, not financial judgment. Used that way, it earns a place in my routine: not as something I constantly monitor, but as a dependable checkpoint for keeping a long-term retirement account organized.
For me, that is the most convincing reason to adopt Thrift Savings Plan. It turns an account I might otherwise ignore into one I can review deliberately, without pretending that a convenient mobile screen can replace a thoughtful retirement plan.
Highlights
- Official access to your TSP account from a mobile device.
- Quickly review balances
- contributions
- and investment allocations.
- Useful for monitoring retirement savings while away from a computer.
- Secure sign-in options help protect sensitive financial information.
- Simple interface focuses on essential account-management tools.
Limitations
- Some advanced planning tools may still require the full TSP website.
- Account updates and transaction processing may not appear immediately.
- Investment choices are limited to the TSP funds available in your plan.
- Occasional maintenance or technical issues can prevent account access.
- Not useful for users without an eligible federal or uniformed-services account.
Frequently Asked Questions
01What is the Thrift Savings Plan app used for?
The Thrift Savings Plan app is designed to help eligible federal employees and members of the uniformed services manage and monitor their TSP retirement accounts. After signing in, users can typically review balances, check contribution activity, view account information, and access plan-related resources. It is mainly a convenience and account-management tool, not a general investment app for the public.
02Who can use the Thrift Savings Plan app?
Access is generally limited to participants with an eligible Thrift Savings Plan account, including qualifying federal civilian employees, members of the military services, and certain other participants associated with the federal retirement system. You will need valid account credentials and may be asked to complete additional identity verification. Downloading the app alone does not create eligibility or open a TSP account.
03Is the Thrift Savings Plan app safe for checking retirement information?
The app is intended for handling sensitive retirement and financial information, so users should sign in only through the official application and keep their device’s operating system updated. Security features may include password protection, multifactor authentication, and automatic session timeouts. Avoid using public Wi-Fi when possible, never share verification codes, and confirm the publisher before installing.
04Can I change contributions or manage investments through the app?
The available account-management options may include reviewing contributions, checking investment allocations, viewing transactions, or accessing certain TSP services, but the exact features can vary by account type and app version. Some actions may redirect you to the official TSP website or require extra verification. Before making an investment or contribution change, review the applicable rules, fees, and potential risks.
05What should I do if I cannot log in or the app is not working?
First, check that you are using the latest version of the app, have a reliable internet connection, and are entering the correct credentials. If multifactor authentication is enabled, make sure you can access the registered verification method. Avoid repeatedly guessing passwords, as this may trigger a lockout. For account recovery, technical errors, or suspicious activity, use official TSP support channels rather than third-party websites.


